When Diet Food Starts Looking Like Something You’d Actually Want
Dieting usually comes with a fairly simple trade-off. You want to eat less, so you give up some of the foods you enjoy.
Korea has been developing a different kind of diet-food market. Instead of simply making existing foods smaller, lighter, or lower in calories, brands are creating snacks that are meant to feel like snacks in their own right.
Protein chips deliver the exact same crunch as standard crisps, low-sugar popcorn retains its movie-theater appeal, and protein cookies eat like traditional bakery treats. Meanwhile, konjac jelly packages vibrant lychee and watermelon flavors into portable, single-serving pouches built for life on the move. The category keeps expanding into more formats, flavors, textures, and packaging styles that make the products feel less like something you buy because you’re dieting and more like something you might actually want to try.
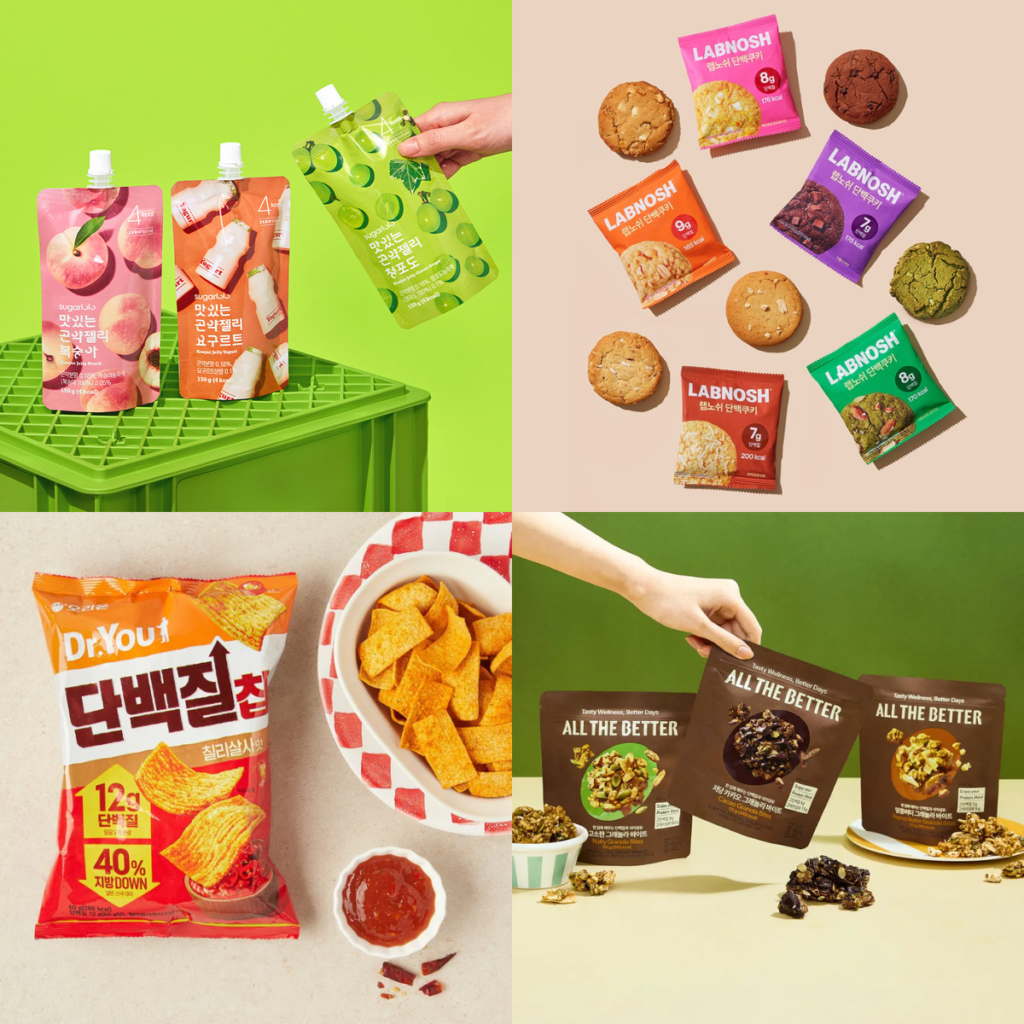
Image: Sugarlolo, Labnosh, Dr. You, All the Better
Competition in Korea is no longer confined to low-calorie alternatives. Diet brands are now competing directly against the broader consumer goods market on flavor, texture, packaging, and sheer novelty. As functional offerings match standard indulgences on pure sensory appeal, the boundary between health food and everyday snacking effectively disappears.
Part I: What Is Happening in Korea
Ditching the Diet Aesthetic
Diet food has traditionally been quite good at making itself look like diet food.
The packaging often tells you exactly what you’re buying before you even read the label. The design tends to emphasize function, calorie control, protein content, or whatever dietary goal the product is meant to serve. It can feel more like a product for people who have already decided to compromise than something you’d pick up simply because it looks good.
Newer Korean diet snacks are moving away from that visual language.
Many borrow the cues of contemporary snack packaging, but with a noticeably newer design sensibility. The category is relatively young, which means brands aren’t necessarily inheriting decades-old packaging conventions. They’re designing for today’s consumer from the start.
The result can look more playful, polished, indulgent, or even more fashion-conscious than some of the conventional snacks around it.
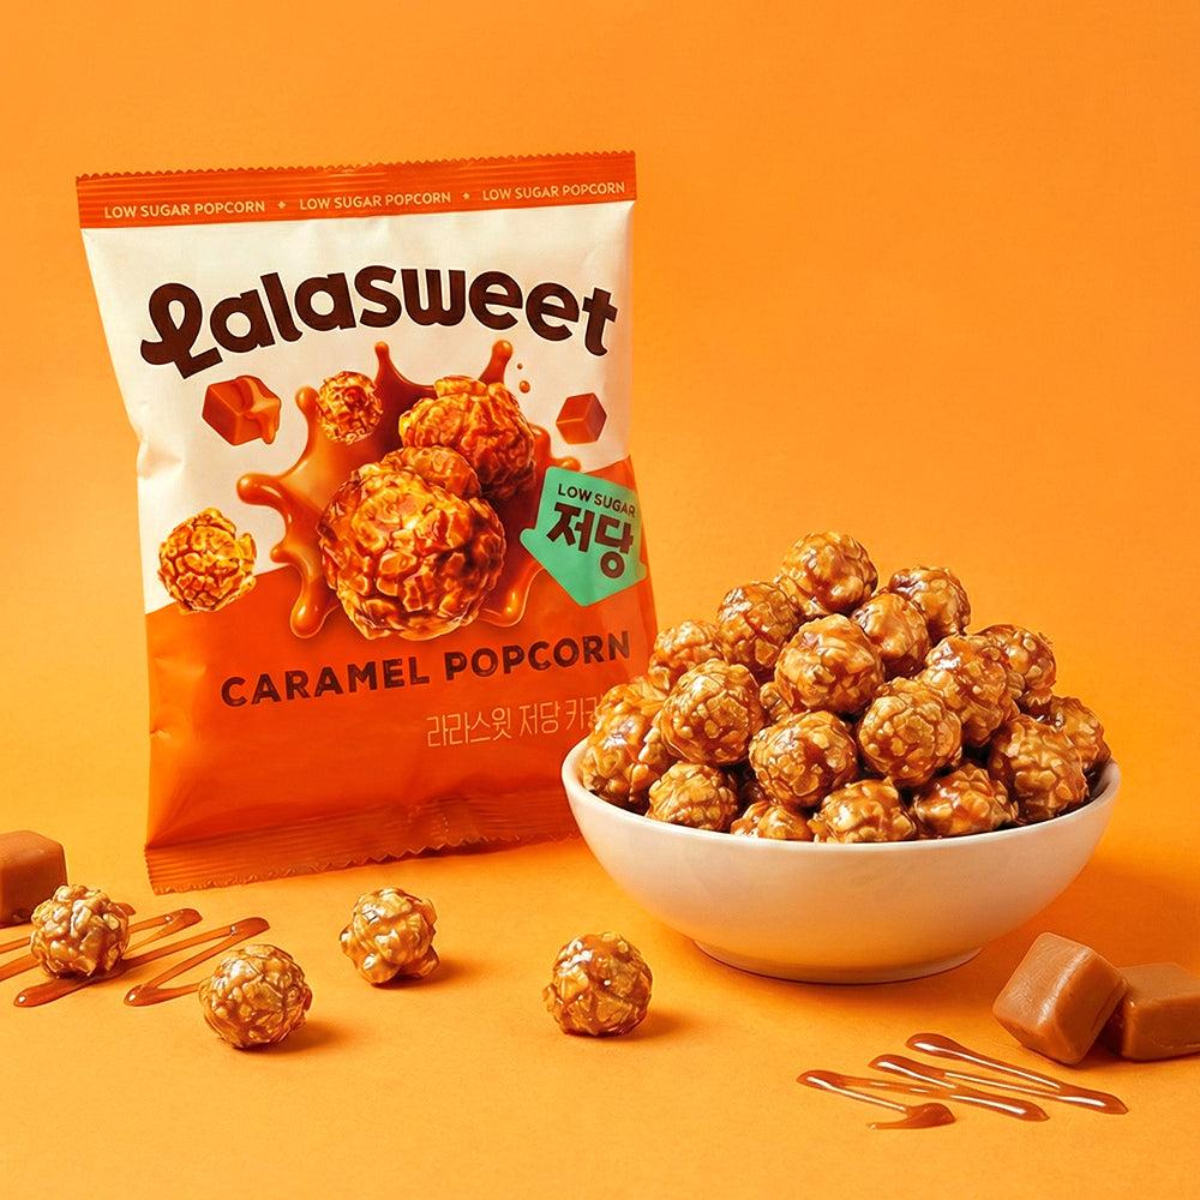
Image: Lalasweet
Mix these products into a standard convenience-store aisle and the traditional health-food markers disappear. Packaging isn’t just serving an aesthetic upgrade here. It is repositioning the entire category to appeal to everyday buyers rather than just strict calorie-counters.
A Diet Snack Becomes a Category
Korean brands now offer diet-oriented versions of many of the foods consumers already understand as snacks. Orion’s Dr. You Protein Chips bring protein into a familiar chip format. Binggrae’s The Protein Pop Chips take a lighter, puffed approach, while Fromeat Protein Chips and Cruntin’s 5mm Whole Potato Chips stay closer to the crunchy potato-chip experience. Labnosh Protein Cookies move into sweet snacking, while Lalasweet’s Low-Sugar Popcorn takes an everyday movie-night format and gives it a diet-friendly positioning.
The point isn’t that Korea has a lot of diet snacks. It’s that there are now enough of them to create choice.
Consumers can choose between something crunchy, sweet, salty, light, protein-focused, or simply low in calories without leaving the broader category. That changes the behavior around diet food. Instead of asking what they have to give up, consumers can start asking which product they want.
And that’s when a category starts behaving more like a real food market than a collection of functional substitutes.
The Category Is Starting to Blend Into Everyday Retail
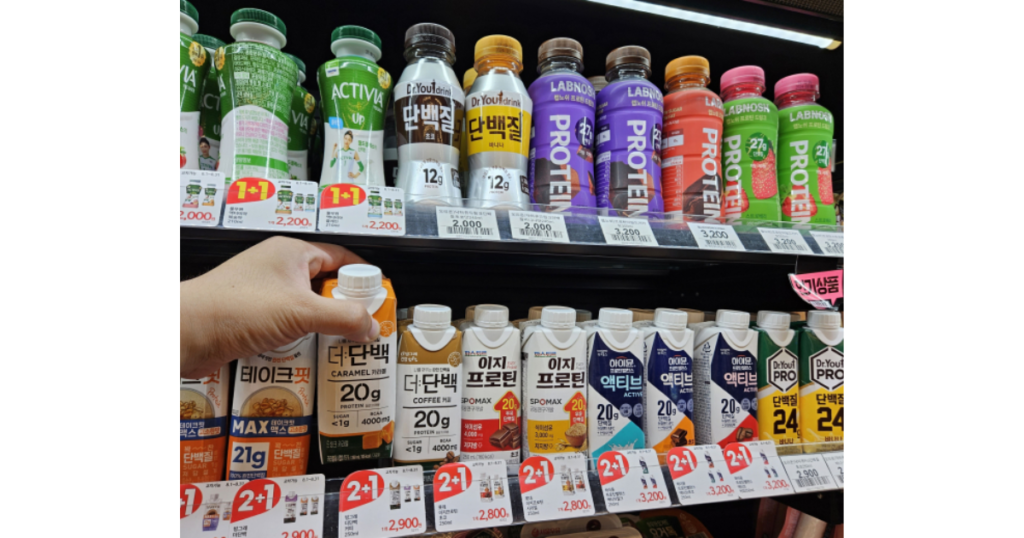
Image: Sedaily
The category is also becoming easier to encounter without actively looking for “diet food.”
Korean convenience stores already carry products such as protein shakes, packaged chicken breast, zero-sugar drinks, and konjac jelly as part of their everyday food selection. Diet-oriented snacks are still less consistently represented than these products, but the boundary is already beginning to blur.
Olive Young provides another important route into the category. Because consumers already visit the retailer for beauty, wellness, and lifestyle products, diet snacks can be discovered in an environment where health-conscious consumption is already part of the shopping mindset. A consumer doesn’t necessarily have to identify herself as someone who shops for diet food before encountering the category.
That matters because distribution changes who gets exposed to a product. The easier it is to encounter these foods during an ordinary shopping trip, the less specialized the category begins to feel.
Social media reinforces that shift through Korean food reviewers, lifestyle creators, and everyday consumers who regularly share what they’re eating, buying, and trying. This means that diet-oriented snacks can appear as part of ordinary food content rather than only within explicitly fitness or weight-loss content.
A protein chip can gain traction simply because it tastes good, while a low-sugar snack spreads on social media because the packaging catches the eye. A konjac jelly quickly becomes an must-have essential in their bag not because it belongs in a rigid diet conversation, but because it effortlessly fits into a modern consumer’s routine.
Part II: The Global Question
From Korean Diet Snacks to a Global K-Food Category?
Korean food already has a much larger international footprint than it did a decade ago. Ramen, seaweed snacks, chips, cookies, gummies, beverages, and convenience-store foods are increasingly familiar outside Korea through K-pop, K-dramas, social media, Asian grocery chains, and mainstream retailers.
Korean diet snacks haven’t broken through globally yet, which is exactly why the category is worth tracking right now.
Konjac jelly offers an early example. Korean-style single-serving jelly pouches have already begun appearing outside Korea, including through Asian grocery retailers and selected mainstream channels. Everydaze’s konjac jelly, for example, has appeared at Costco in the United States, while Korean konjac products are also available through H Mart and other Asian retailers.
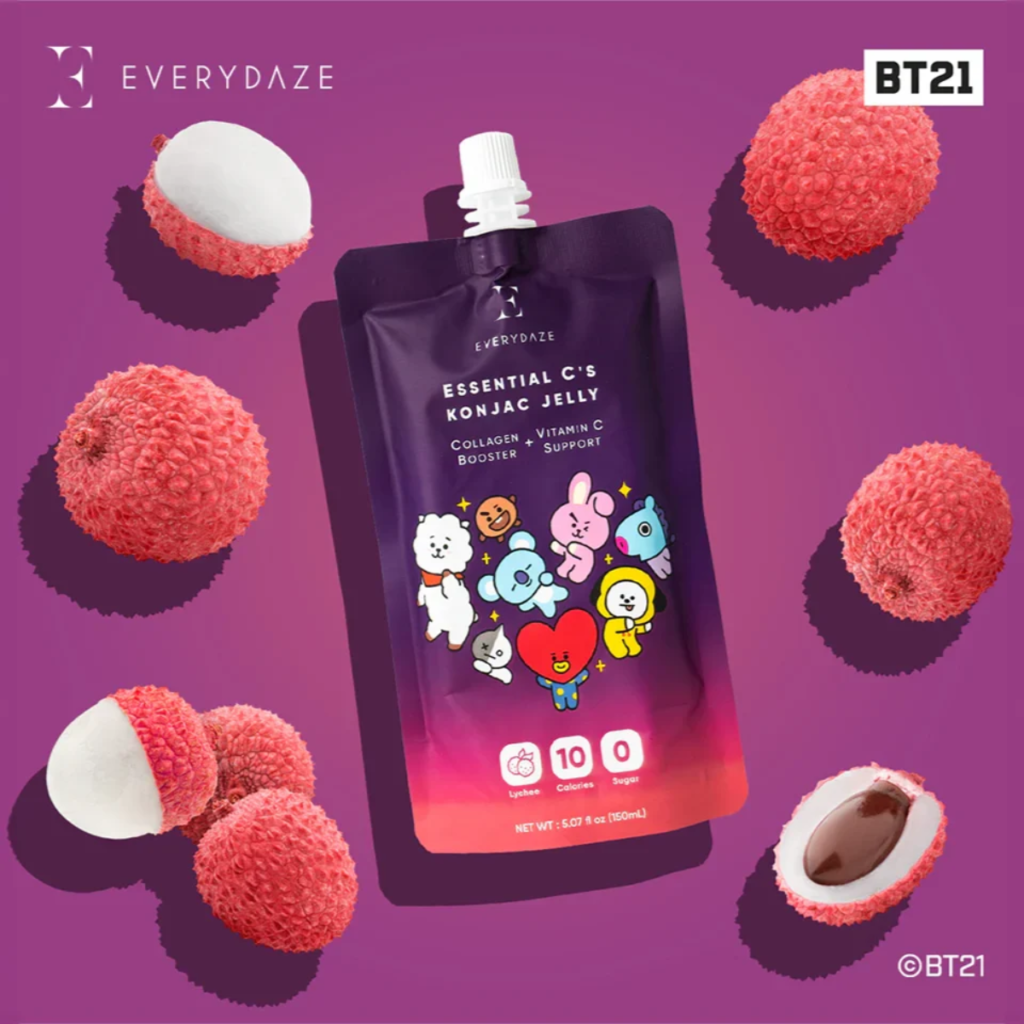
Image: Everydaze
Consumer discovery is happening online too. Reviews and discussions around konjac jelly often focus on the same things that make the category interesting in Korea: very low calorie counts, convenient single-serving formats, and flavors that make the product feel more like a snack than a functional diet product.
While konjac jelly has yet to achieve global scale, its early footprint illustrates how wellness-focused Korean products enter established international distribution paths. The focus now shifts to what happens as the broader category matures.
Korean food is already making the move from Asian grocery shelves into mainstream retailers such as Costco, Walmart, and Target. Korean diet snacks are largely not there yet, with konjac jelly being one of the more visible exceptions. As Korean snacks become increasingly familiar to international consumers, it becomes easier to imagine diet-oriented Korean products following the same path.
But the products that succeed globally will have to compete as food, not simply as Korean products.
A consumer might buy a Korean protein snack the first time out of novelty or cultural curiosity. Then they may buy it a second time because it tastes good, fits their routine, and solves a real daily need. That repeat purchase is what turns a cultural trend into a sustainable category.
The Positioning Question Worth Watching
If Korean diet snacks begin moving into more mainstream international retail, the way brands position them will matter.
Two go-to-market narratives are emerging in this space. One leverages K-food heritage to capture immediate interest, while the other positions the product on flavor and lifestyle fit first, treating its Korean origin as a secondary detail. The latter holds significantly more staying power. Cultural novelty gets a product into the basket once, but flavor and functionality keep it on the weekly grocery list.
That distinction matters for any Korean food brand looking outward. If a product is treated primarily as a Korean novelty, its audience may remain tied to consumers who are actively interested in Korean culture. If the product can stand on its own as a good snack, the potential audience becomes much larger.
The Korean diet-snack market is worth watching because it reveals what happens when functional food is forced to compete directly with ordinary indulgences on taste, design, and daily convenience.
Flavor, texture, packaging, and convenience set the baseline. Long-term category winners are the ones that turn an initial trial into a daily habit.
Market Insight
When Diet Products Have to Compete With Everything Else
The more useful lesson from Korea isn’t that diet snacks should look more attractive. It’s that a mature diet market eventually creates a much harder competitive environment.
Korean diet snacks are not just fighting for share within the health aisle. They are competing against standard snacks consumers already buy and crave. That sets a much higher bar. A low-calorie chip still needs an undeniable crunch, and a reduced-sugar treat still needs to taste like an indulgence. If a functional snack cannot match traditional junk food on pure enjoyment, consumers will simply reach for the original.
Once the category reaches that point, innovation starts moving into the details. New flavors, textures, formats, portion sizes, packaging concepts, and usage occasions become ways for brands to differentiate without abandoning the functional reason the category exists in the first place.
For global strategists, this is the signal worth tracking. The takeaway is not simply identifying which diet snacks are launching, but analyzing what Korean consumers are comparing them against and which functional attributes are shifting from novel perks into baseline expectations. A category enters its most lucrative phase the moment consumers stop judging products against niche diet alternatives and start holding them to the standards of everything else in their pantries.
When “Diet” Stops Being the Main Selling Point
The Korean diet snack market is not interesting because it invented healthier alternatives. The true signal lies in where the category is heading. Functional, diet products are no longer graded on a curve. They must look, taste, and perform like ordinary food, giving consumers a clear reason to choose them over traditional impulse buys.
That puts Korean diet snack brands in an unusual position because they’re competing against the entire snack market.
Whether that eventually turns Korean diet snacks into a meaningful global K-food category is still an open question. Distribution, price, taste preferences, and attitudes toward dieting will all determine how far the category travels.
Korea is already demonstrating what happens when functional snacks stop demanding consumer compromise. The true inflection point in this market is not merely when a health-conscious snack becomes indistinguishable from a standard indulgence. It is when consumers stop categorizing it as a diet product altogether.
Sources
- Costco product listing — Everydaze Essential C’s Konjac Jelly, Collagen + Vitamin C, 30-pack (20 calories, 2,500mg collagen, 500mg vitamin C, multiple flavors): https://www.costco.com/p/-/everydaze-essential-cs-konjac-jelly-collagen-vitamin-c-30-pack/4000039904
- asipoftexas.com — Everydaze Konjac Jelly Costco Review (consumer review including flavor, satiety notes, and practical use): https://asipoftexas.com/everydaze-konjac-jelly-costco/
- Walmart product listing — Tastelli Konjac Jelly (10 calories, collagen + vitamin C): https://www.walmart.com/ip/seort/605371802
- Walmart product listing — Jelly.B Drinkable Konjac Jelly (Korean brand, lychee/watermelon/grape/apple flavors, consumer reviews): https://www.walmart.com/ip/seort/15196765070
- Korea Agro-Fisheries & Food Trade Corporation (K-Food Trade) — “K-Diet Foods for Everyday Wellness”: https://www.k-foodtrade.or.kr/brd/m_106/view.do?seq=738&srchFr=&srchTo=&srchWord=&srchTp=&srchTp2=&srchWord2=&itm_seq_1=0&itm_seq_2=0&multi_itm_seq=0&company_cd=&company_nm=&page=1
- Korea Agro-Fisheries & Food Trade Corporation (K-Food Trade) — “Diversification of Korea’s Snack Market”: https://www.k-foodtrade.or.kr/brd/m_106/view.do?seq=718&srchFr=&srchTo=&srchWord=&srchTp=&srchTp2=&srchWord2=&itm_seq_1=0&itm_seq_2=0&multi_itm_seq=0&company_cd=&company_nm=&page=1
- Korea Agro-Fisheries & Food Trade Corporation (K-Food Trade) — “Korean Snack Market Trends”: https://www.k-foodtrade.or.kr/brd/m_106/view.do?seq=694&srchFr=&srchTo=&srchWord=&srchTp=&srchTp2=&srchWord2=&itm_seq_1=0&itm_seq_2=0&multi_itm_seq=0&company_cd=&company_nm=&page=1
- Seoul Economic Daily — “Low-Sugar Trend Sweeps Korea’s Food Industry, Driving Sales Surge”: https://en.sedaily.com/finance/2026/05/21/low-sugar-trend-sweeps-koreas-food-industry-driving-sales