A New Direction
Global K-beauty established its dominance through topical innovation, flooding shelves with targeted ampoules, barrier creams, and clinical actives. The vocabulary kept expanding, and so did the shelf.
Today, Korean consumers are now shopping in a facial skincare market that is almost absurdly well developed. There are products for nearly every concern, texture preference, price point, and stage of a routine. And when that isn’t enough, there is no shortage of dermatology and aesthetic clinics offering professional treatments.
In response, innovation has shifted to technology. Home beauty devices are replacing traditional serums as the primary driver of routine upgrades, bringing clinical equipment like EMS, RF, LDM, and HIFU directly onto their vanity table.
This device movement does not stem from a sudden obsession with devices, but from a pragmatic consumer base accustomed to clinic-grade results seeking high-efficiency, at-home alternatives to differentiate their routines.
When Skincare Gets Crowded
Korean consumers are unusually educated skincare shoppers. They know the basics of ingredients, understand how to build a routine around a concern, and have spent years being introduced to new actives, textures, and product formats.
The problem for brands is that the market has become very good at giving them something to buy.
Facial skincare in Korea is crowded at almost every level. A consumer can find a product for dryness, pigmentation, pores, sensitivity, firmness, barrier care, and everything in between, with multiple textures and price points competing within each concern. New products continue to launch at a pace that makes meaningful differentiation increasingly difficult.
And Korean consumers have another option that makes the bar even higher. Professional skincare has become a familiar part of the beauty routine, particularly for consumers looking for results that topical products have a harder time delivering. Fine lines, wrinkles, skin elasticity, collagen production, and sagging are areas where consumers increasingly understand that there is a ceiling to what a bottle of skincare can realistically accomplish. Instead, clinic visits can become the next step when a daily routine is no longer enough for the results they want.
That is also why the appeal of a home device is fairly easy to understand. It cannot reproduce a professional treatment, and brands should not pretend otherwise. But for a consumer who already understands the difference between topical skincare and clinical treatment, a device offers something in between. It brings technology into the home and gives consumers another route toward the kinds of results they have already learned to seek from professional care.
In that sense, the device category is less about replacing skincare than about acknowledging where skincare starts to reach its limits.
This is where the economics of innovation start to change. When consumers already understand the formulation landscape and can roughly assess what a product is trying to do from its ingredients and claims, another active ingredient is not necessarily enough to make a launch feel new.
Meaningful topical innovation increasingly requires proprietary ingredients, genuinely novel delivery systems, stronger clinical evidence, or manufacturing capabilities that smaller and newer brands may not have access to.
This helps explain why some brands are experimenting with increasingly elaborate textures, packaging, and product formats. When the problem being solved becomes harder to find, brands start getting creative about how they present the solution.
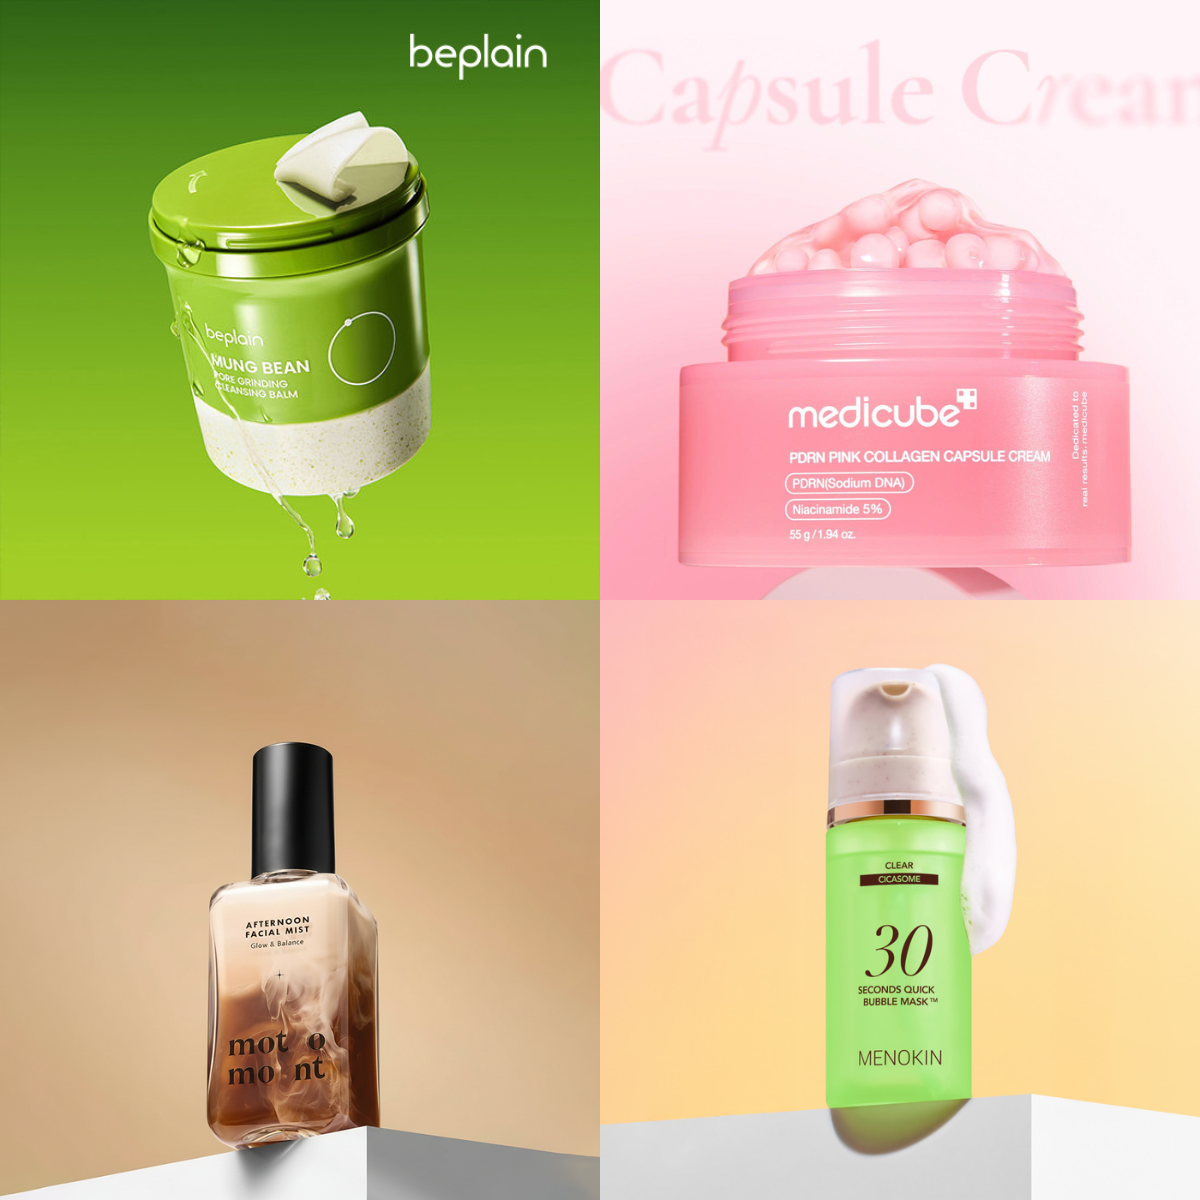
Image: Beplain, Medicube, motomont, Menoskin
Devices offer something much harder for another serum to imitate. They give brands an entirely different dimension on which to compete.
Consumers Were Already Ready
The Korean consumer picking up a home beauty device is not starting from zero. They have probably already encountered the logic behind it somewhere else.
Korean consumers are accustomed to professional skincare treatments, from laser procedures and RF lifting to ultrasound-based treatments and skin boosters. They may have experienced these treatments themselves, heard about them from friends, or simply absorbed the vocabulary through celebrities and beauty content. Procedures such as Ulthera and Shurink are not obscure pieces of clinical terms to a consumer who has spent years following Korean beauty culture.
That matters because a home device does not have to introduce the idea that technology can be used to improve the skin because that idea is already familiar.
Korean skincare culture has never been particularly hesitant about adding another step if the payoff seems worth it. Gua sha is a good example. It’s not essential to maintaining healthy skin, yet it has become a familiar part of some routines because consumers are willing to put in more effort when they believe it can improve results.
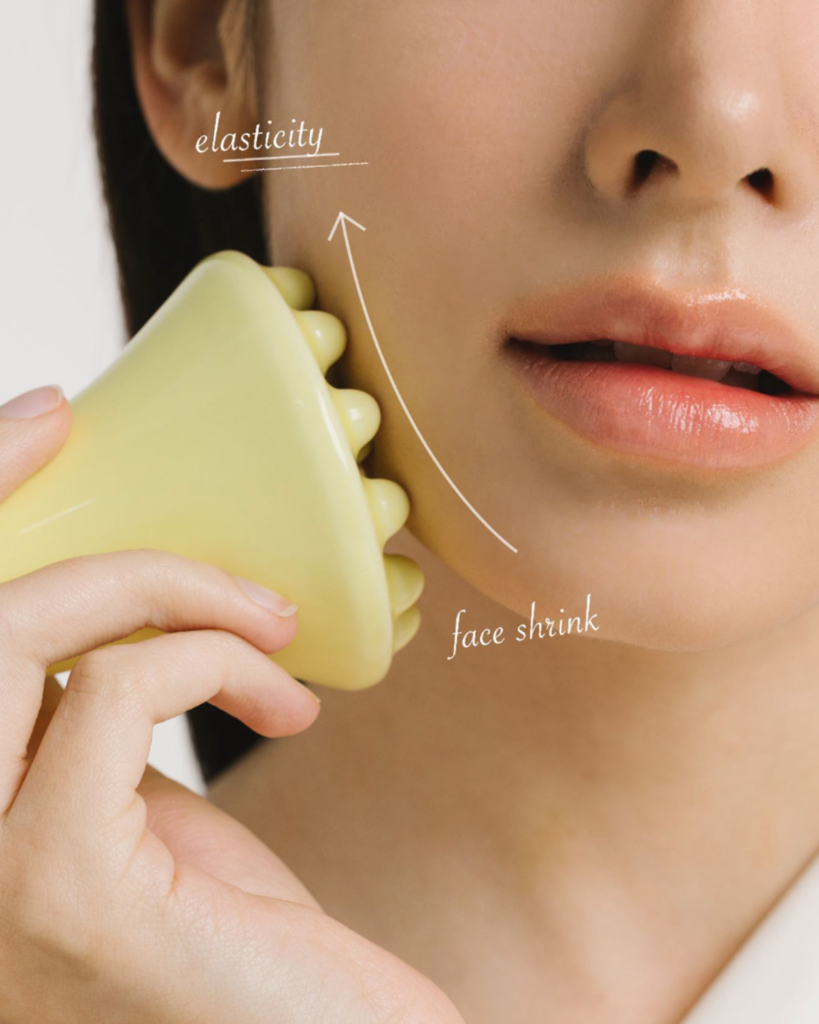
Image: Flona
That mindset makes devices much easier to introduce. Consumers already understand the idea of choosing a treatment based on the result they want. Give them a new technology and they are likely to start comparing it with the other options, rather than wondering why the extra step exists in the first place.
That level of comparison is a sign of a category becoming more sophisticated. Once consumers start sorting through technologies, use cases, and expected results, brands are no longer selling the idea of the category.
The Active Routine
There is a reason skincare devices are so well suited to the way Korean beauty consumers already approach their routines. A topical asks consumers to apply something but a device asks them to actively do something, whether that means moving it across the face, following a treatment mode, choosing a setting, or adjusting the routine around a specific concern.
Gua sha already made this kind of behavior familiar. The difference is that devices give the extra step a layer of technology, with different mechanisms designed around different results.
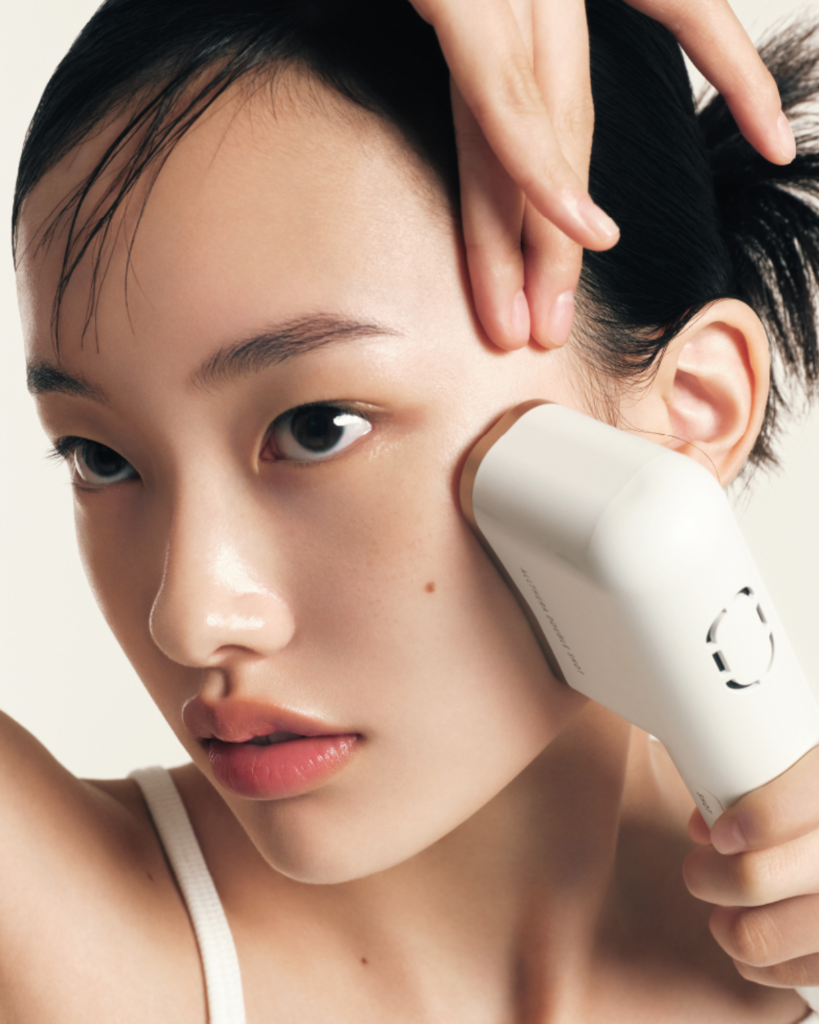
Image: Singles Korea
That variety is becoming increasingly visible in Korea. EMS, RF, LDM, and HIFU are not interchangeable technologies, and Korean consumers are beginning to learn what each one is supposed to do. Lifting, firmness, hydration, texture, and other concerns can now lead consumers toward different devices rather than another serum.
You can see the category becoming more sophisticated in the content around it, too. Creators are comparing technologies, explaining how different devices work, and weighing which products make sense for particular concerns and budgets.
Once consumers start comparing technologies instead of simply looking for the newest device, the category has moved into a different stage of maturity.
A New Way to Compete
For brands, part of the appeal is fairly obvious. When facial skincare is already crowded with products competing on ingredients, claims, textures, packaging, price, and increasingly narrow points of differentiation, a device creates a completely different proposition.
Unlike topicals, beauty devices excel at visual proof. Creators can demonstrate application techniques, compare technological modes side by side, and integrate the physical product naturally into engaging routine content.
That is particularly valuable while the category is still relatively new. There is plenty left to explain, which gives creators a reason to make comparison videos, reviews, tutorials, and “which device should I buy?” content. A category that has not yet been flooded with the same five content formats gives creators more room to find an angle.
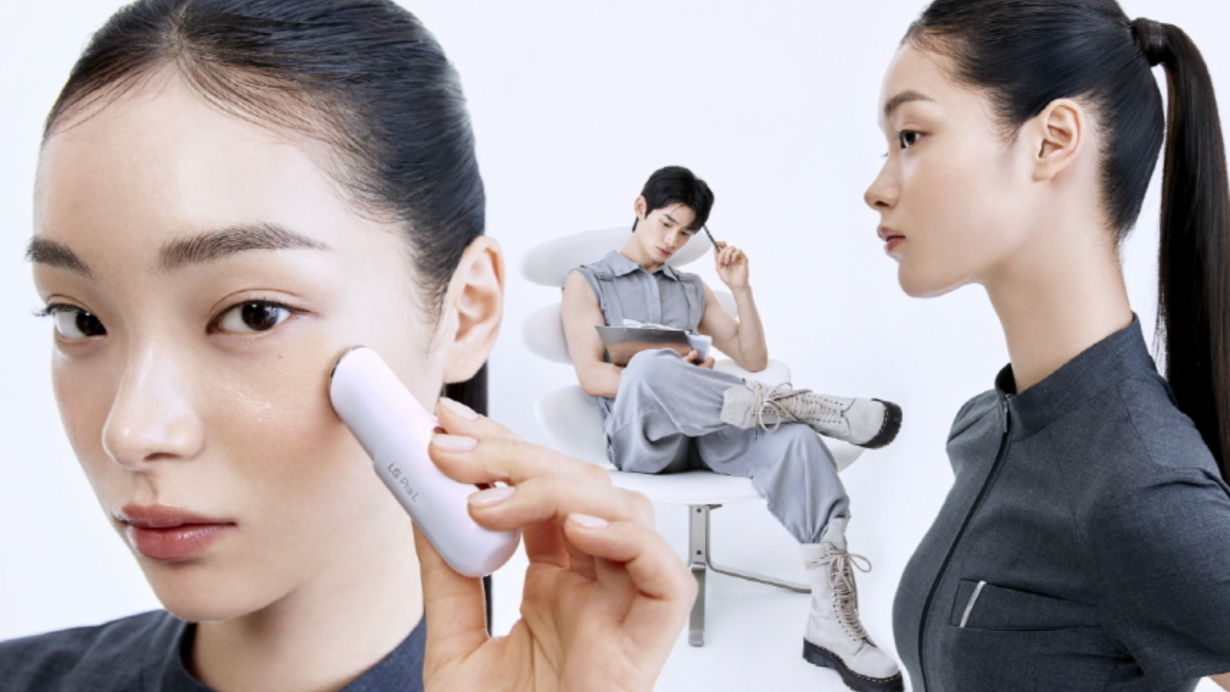
Korean brands are already taking advantage of that space. LG has brought its consumer electronics expertise into beauty through Pra.L, while brands including thome, Quadthera, botem, and Glow.M are developing devices using different technologies and positioning.
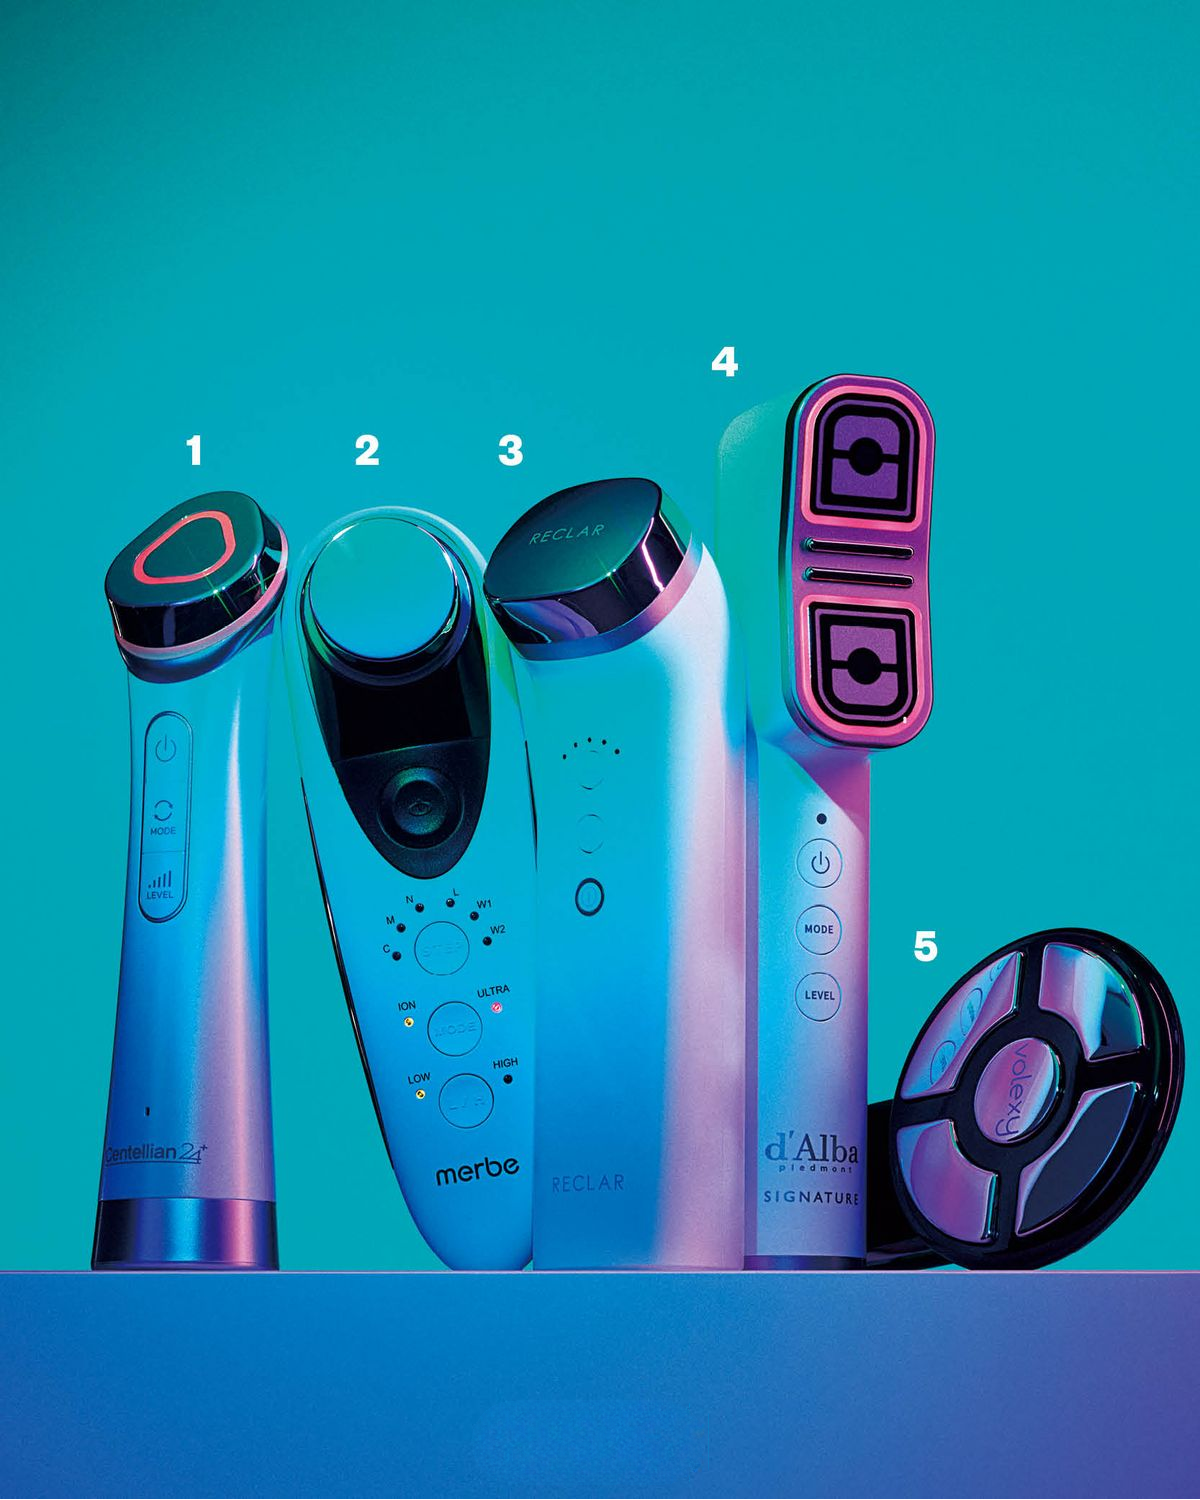
Image: Cosmopolitan Korea
Medicube provides the clearest evidence that this is not confined to Korea. In January 2026, APR announced that cumulative global sales of MEDICUBE AGE-R devices had surpassed 6 million units, with more than 60% of cumulative sales generated outside Korea. The brand had reached 3 million cumulative units by the end of 2024 and added another 2 million in the first nine months of 2025.
Image: Medicube
The acceleration is more interesting than the headline number. Korean beauty devices have already proved that they can travel. The question now is whether Medicube remains the standout success or becomes the brand that opened the door for a much larger Korean device category.
Media Teaches the Category
Korean skincare devices are not being introduced through product pages alone. A lot of the education is happening in public, through the people consumers already follow for beauty advice.
Korean celebrities have increasingly shown their home devices in personal YouTube content, interviews, and television appearances. That matters because these are often the same people who have access to professional skincare treatments and openly discuss the procedures they receive. When they show a device being used at home, the product sits within a much larger beauty routine that consumers already understand.
Creators take that one step further. Reviews increasingly go beyond whether a device is “good” and get into the differences between technologies, what each device is designed to address, how they compare in price, and which one might make sense for a particular concern.
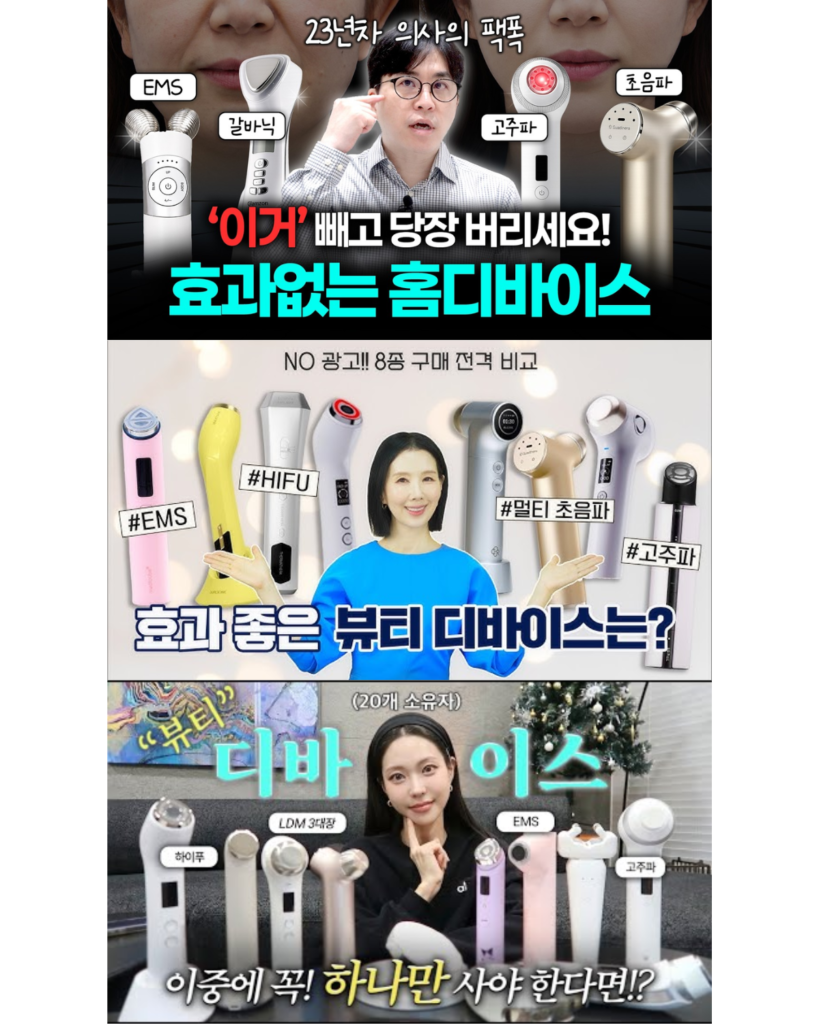
Image: Director Pi, 헤이즐 Heizle, Dr. Lee Yong-seok, the Lifting Doctor
There is still enough white space in the category for this content to feel useful rather than repetitive. Compare that with facial skincare, where another review can easily disappear into an endless stream of similar products. Devices give creators something new to explain, demonstrate, compare, and test.
Korea’s broader consumer ecosystem makes that especially powerful. Celebrities generate attention, creators provide the tutorial, and retailers give it space. Every touchpoint reinforces the product until it takes over the market.
Skincare devices happen to be almost perfectly designed for this system. Visually engaging and easy to demonstrate, the category turns product education directly into high-converting media.
What Global Brands Can Learn
The global success of Korean beauty devices extends far beyond impressive sales figures. The category flourished domestically because Korean consumers were already skincare experts. They routinely invested in professional clinic procedures, embraced multi-step regimens to elevate skin health, and turned to specialized creators for purchasing guidance.
The device market succeeded because the target audience was already trained. The physical devices simply gave those established habits a fresh, accessible home.
That structural shift offers the primary lesson for global brands. Breakthrough categories rarely require building demand from scratch. Often, the best commercial opportunity involves identifying an existing consumer habit that has reached sophistication to support a new solution.
For global brands, this demands looking past currently trending items and asking what habits target consumers have already developed. When audiences actively use specialized tools, book clinical treatments, analyze active ingredients, or consume educational content around a specific concern, the next commercial opportunity sits immediately adjacent.
Korea’s emerging device category shows exactly what happens when consumer knowledge outgrows traditional skincare bottles.
Looking at Your Brand Strategy
Uncovering the hidden signals in Korean consumer culture requires looking past surface-level trends. If you are exploring how Korean market shifts, consumer behavior, and category movements can open new opportunities for your business, Siseon works with global teams to turn these observations into strategic advantage.
To discuss custom research, field intelligence, or strategic advisory for your team, connect with us directly at hello@siseonhq.com or fill out the contact form.
Sources
- PRNewswire / APR Co., Ltd. — “APR Exceeds 6 Million Units in Global Sales of MEDICUBE AGE-R Beauty Devices” (6 million unit milestone, 60%+ outside Korea, Booster Pro as flagship, APEC selection, modular expansion, January 29, 2026): https://www.prnewswire.com/apac/news-releases/apr-exceeds-6-million-units-in-global-sales-of-medicube-age-r-beauty-devices-strengthening-leadership-in-home-beauty-tech-302671022.html
- The Investor / Korea Herald — “APR’s Medicube hits 5m global sales amid home beauty boom” (5 million milestone September 2025, launch history from 2021, 3 million by end 2024, 2 million in 9 months of 2025): https://www.theinvestor.co.kr/article/10599112
- Cosmetics Design Asia — “K-beauty firm behind Medicube sees global expansion propelled by demand for cost-effective next-gen devices” (CES 2024 participation, US product lineup, brand positioning around beauty-device lifestyle): https://www.cosmeticsdesign-asia.com/Article/2024/01/08/Firm-behind-medicube-sees-global-expansion-propelled-by-demand-for-cost-effective-next-gen-devices/
- APR Co., Ltd. (KOSPI listed) — company background, MEDICUBE, MEDICUBE AGE-R, and Aprilskin brand portfolio: https://www.cbinsights.com/investor/apr
- The Allure Edition — “Medicube Korean Device: Is It Worth It?” (consumer review, viral timeline 2022-2024, creator coverage, product positioning): https://www.theallureedition.com/medicube-korean-beauty-device/